

A shelf is a contract that renews every quarter. Over five quarters, 99 skincare brands lost theirs.
- 57 exits at Ulta and 42 at Sephora, Q1’25 to Q3’26
- 567 ranked products went with them
- Every exit is verified brand by brand on the retailer’s own site
More from Jump Accelerator:
Summary: Q3 2026 exits at a glance
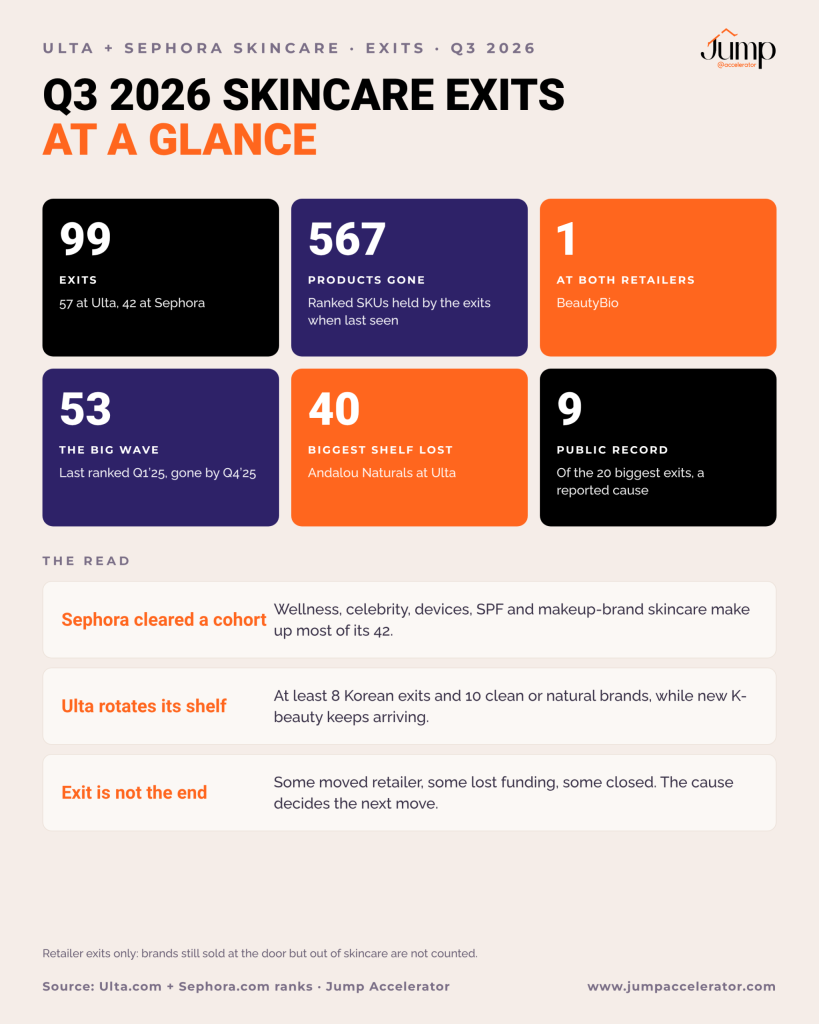
- 99 exits: 57 at Ulta, 42 at Sephora.
- 1 brand exited both retailers: BeautyBio. Nutrafol left Sephora; at Ulta it moved out of skincare into wellness.
- The big wave was early: 53 brands last ranked in Q1’25 and were gone by Q4’25.
- Biggest shelf lost: Andalou Naturals, with 40 ranked products at Ulta.
- Sephora cleared a cohort: wellness, celebrity, devices, suncare and makeup-brand skincare.
- Ulta rotates its shelf: Korean and clean-label brands left while new K-beauty kept arriving.
The full exit roster, with every brand’s last quarter, shelf held and status, is in the Skincare Q3 2026 Ulta + Sephora report.
How we count an exit
- Exited = no longer sold at that retailer. Checked on the retailer’s site, brand by brand.
- Not counted: brands that dropped off the skincare board but still sell at that retailer. Moon Juice is still sold at Ulta, outside skincare. Off the board is not off the retailer.
- Last seen = the last quarter the brand ranked. The rank data shows when a brand stopped appearing, never why.
- Reasons come only from trade press or live brand and retailer pages, and each one is labelled.
Ulta: the 10 biggest skincare exits
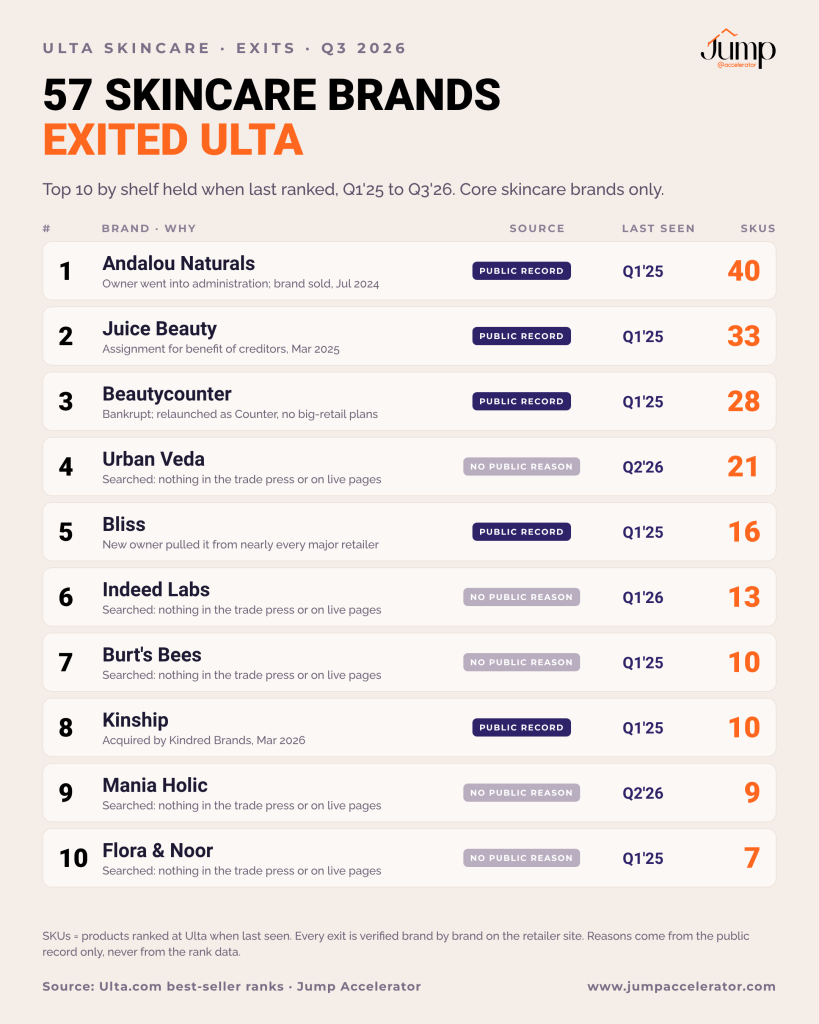
The read: Ulta treats K-beauty as a rotating test shelf.
- At least 8 Korean brands left: Isntree, rom&nd, Skinfood, VDL, KUNDAL, Jungsaemmool, Mania Holic and BEAUND.
- In fast, out fast: Ulta added 13 K-beauty brands in one wave in July 2025. rom&nd was one of them and is already gone, while Ulta’s K-beauty sales still grew double digits in Q2 2026.
- Same brand, opposite outcome: Jungsaemmool is gone from Ulta and climbing at Sephora.
- Clean and natural took the hardest hit: Andalou Naturals, ACURE, Juice Beauty, Kinship and Beautycounter all left.
- Men’s grooming and drugstore thinned out: Beast, Duke Cannon and Every Man Jack; Nivea, Bioré and Freeman.
- The quote that explains the shelf: Kinship’s co-founder said a specialty retailer added “23 new sunscreen SKUs in a single season” while Kinship “spent three years fighting to maintain shelf space.” (Beauty Independent, Mar 2026)
Ulta brings brands in fast, shelf demand decides, and the slow ones go.
Sephora: the 10 biggest skincare exits
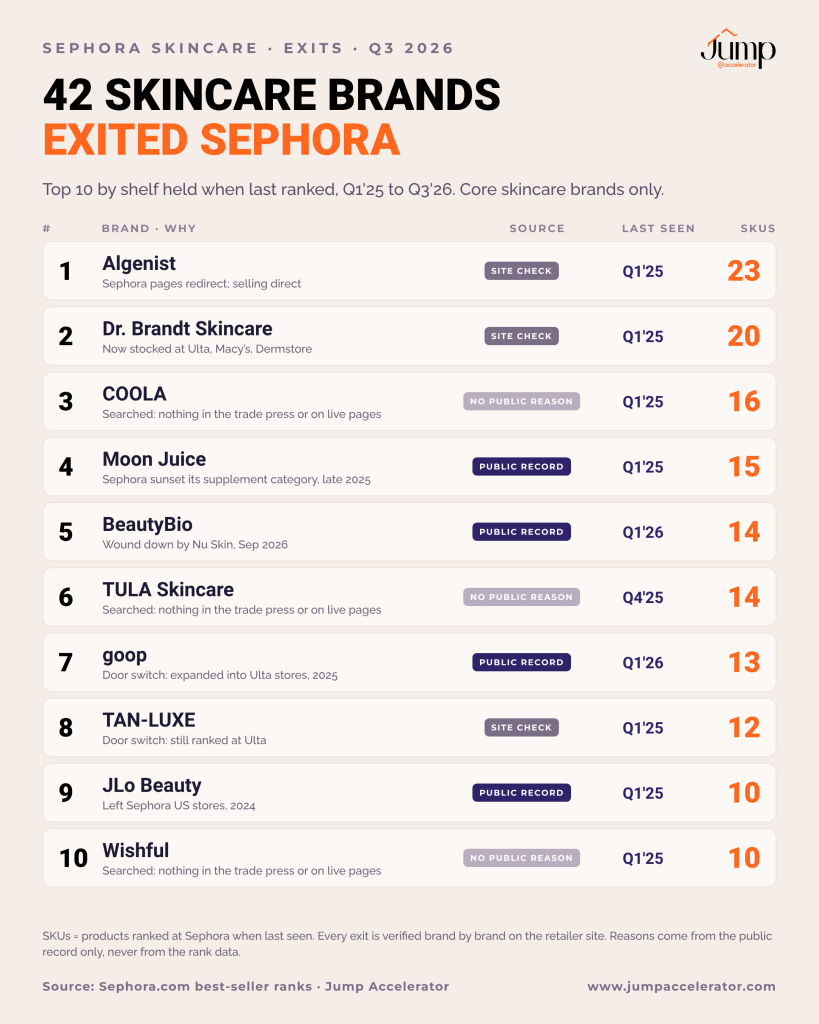
The read: Sephora is clearing out whole segments, including its pandemic-era wellness and celebrity bets.
- Wellness, 7 brands: mostly supplements and sexual wellness, including Moon Juice, Nutrafol and The Nue Co.
- Celebrity and founder fame, 6: including JLo Beauty, ROSE INC, The Outset, goop and Wishful.
- Devices, 5: including FOREO, Therabody and BeautyBio.
- Suncare, 5: including COOLA and Hello Sunday.
- Makeup brands and spin-off lines, 5: including Smashbox and Buxom.
- The rest are clean-era indies and older prestige names, including Herbivore, Algenist, Dr. Brandt and TULA.
- Where the space went: Korean brands and hero-led founder brands. No Korean brand left Sephora. Four of its seven fastest climbers are Korean, and Biodance climbed from #28 to #2. rhode has held #1 since Q4’25 with 22 ranked products. From this fall, Olive Young curates a dedicated K-beauty zone inside Sephora. See the climbing blog.
Exited at both retailers
- BeautyBio: gone from Sephora by Q2’26 and from Ulta by Q3’26. Nu Skin wound the brand down in September 2026.
Not a double exit: Nutrafol. It left Sephora by Q2’26. At Ulta it dropped off the skincare board but is still sold, now in wellness. Off the board is not off the retailer.
Ulta vs Sephora: two shelves, two strategies
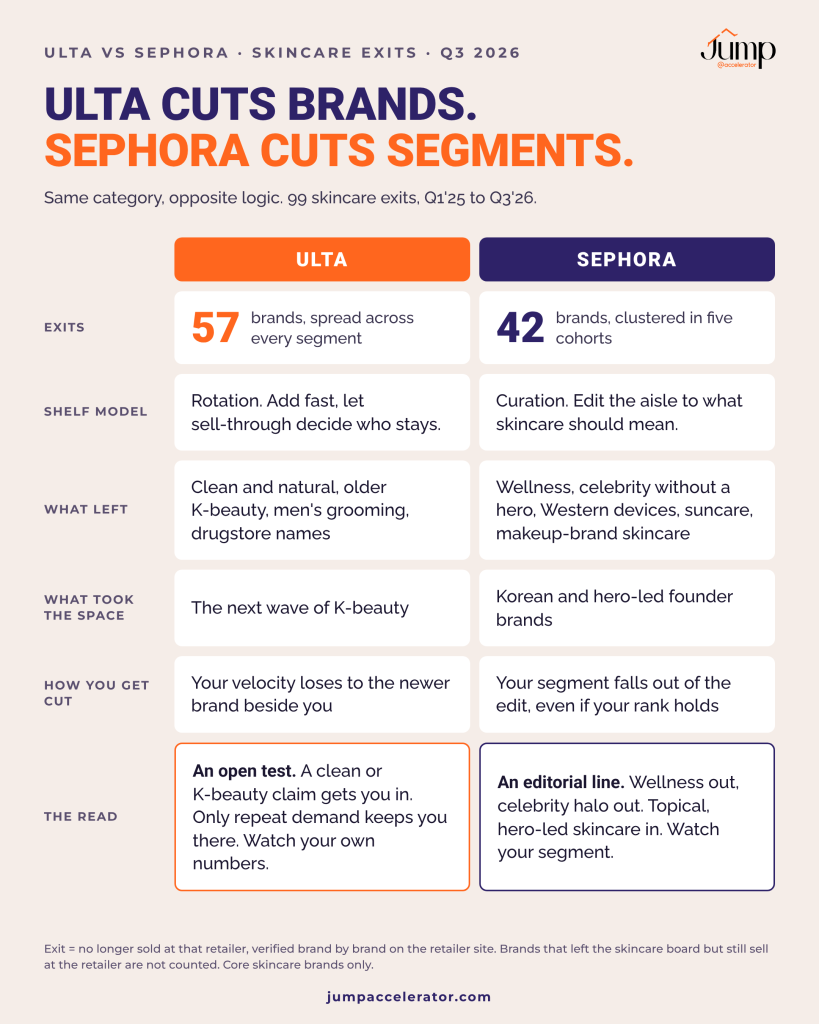
| Ulta | Sephora | |
|---|---|---|
| Exits | 57 brands, spread across every segment | 42 brands, clustered in five cohorts |
| Shelf model | Rotation. Add fast, let sell-through decide who stays. | Curation. Edit the aisle to what Sephora wants skincare to mean. |
| What left | Clean and natural (Andalou Naturals, Juice Beauty), older K-beauty (Isntree, Skinfood), men’s grooming (Duke Cannon), drugstore names (Nivea, Bioré) | Wellness (Moon Juice, Nutrafol), celebrity without a hero (JLo Beauty, ROSE INC), Western devices (FOREO, Therabody), suncare (COOLA), makeup-brand skincare (Smashbox) |
| What took the space | The next wave of K-beauty | Korean and hero-led founder brands. Four of the top seven climbers are Korean. |
| How you get cut | Your velocity loses to the newer brand beside you | Your segment falls out of the edit, even if your rank holds |
| The read | An open test. A clean-label or K-beauty claim gets you in the door. Only repeat demand keeps you there. Watch your own numbers: ranked products and best rank, quarter on quarter. | An editorial line. Wellness out, ingestibles out, celebrity halo out. Topical, hero-led skincare in. Watch your segment: when brands like yours slide in the same quarter, or you hold at Ulta but fade at Sephora, that is the edit, not your demand. |
Both shelves churn, in different places. Ulta cuts from the bottom: 57 exits. Sephora reshuffles the top: only 13 of its top 30 brands from Q1’25 are still there, against 19 at Ulta. A top seat at Sephora is rented.
The market itself: the story brand is losing
- Clean with a good story no longer earns shelf space. At Sephora, Drunk Elephant, Kosas, ILIA and Saie are all sliding. They are losing to K-beauty, with better textures at lower prices, and to derm brands that make efficacy claims: ISDIN, Medik8 and Paula’s Choice are climbing.
- Western devices are losing to Korean ones. BeautyBio’s sales fell nearly 67% in Q1 2026 as K-beauty devices like Medicube moved in, and Nu Skin wound the brand down (Beauty Independent, Sep 2026). Medicube is now #5 at Ulta.
- Fame needs a hero. Fame without a hero product doesn’t stick. rhode shows that fame with one does.
The early warnings
Watch for these two to three quarters before an exit:
- Ranked products halve quarter on quarter.
- The best product drops outside the top 500.
- Store shelves pulled, with the brand left online only.
What this means for your brand
Rank is the output. The shopper funnel is the input. The brands that kept their shelf worked every stage of it, not just the sell-in.
- Placement. Know where you actually sit: which aisle and where in it, from eye level and endcap to bottom shelf, how many doors carry you, and which board you rank on online. Off a skincare board is not off the retailer, and a pull from stores to online only is an early warning.
- Attention. Win the shopper in the aisle and on the screen: packaging that reads from three feet, testers that work, reviews and retailer search that put you in the first row, and the social demand you pull into both. A crowded shelf rewards the brand shoppers already came looking for.
- Merchandising. One clear hero, enough facings and stock to keep it on the shelf, the right price tier and a product page that converts. An empty peg loses the sale and the rank with it. A demand problem needs a new hero product, not a new retailer.
- Activation. Turn attention into repeat: store staff who recommend you, sampling at the fixture, retailer events, loyalty and retail media. Fund it before you win the shelf; a national rollout needs working capital to keep stock on it.
Then match the funnel to the retailer. At Ulta, every stage has to move velocity. At Sephora, every stage has to prove you belong in the edit. Track your path every quarter. The board warns you before the buyer does.
Get the full picture
The Skincare Q3 2026 Ulta + Sephora report covers:
- every exit, left-category and off-board brand
- brand ranks at both retailers, with the 2-year trajectory
- climbers, peakers and decliners
- momentum 2x2s
- shelf crowding by price tier
- brands common to both retailers
711 brands · 9,913+ products · 20 category boards · 5 quarters.
Jump Accelerator: I spot and scale emerging beauty brands and retail destinations that stick, fueled by decoded market intelligence.