
Suzanne LeRoux
Rohit,
This is incredibly useful work-especially the sections on top-ranking brands (and why), individual product rankings, category winners, and the white space vs. saturation analysis. That’s where it becomes most strategic for me. Some sections feel a little dense. Overall, the competitive visibility is excellent.”
Suzanne LeRoux
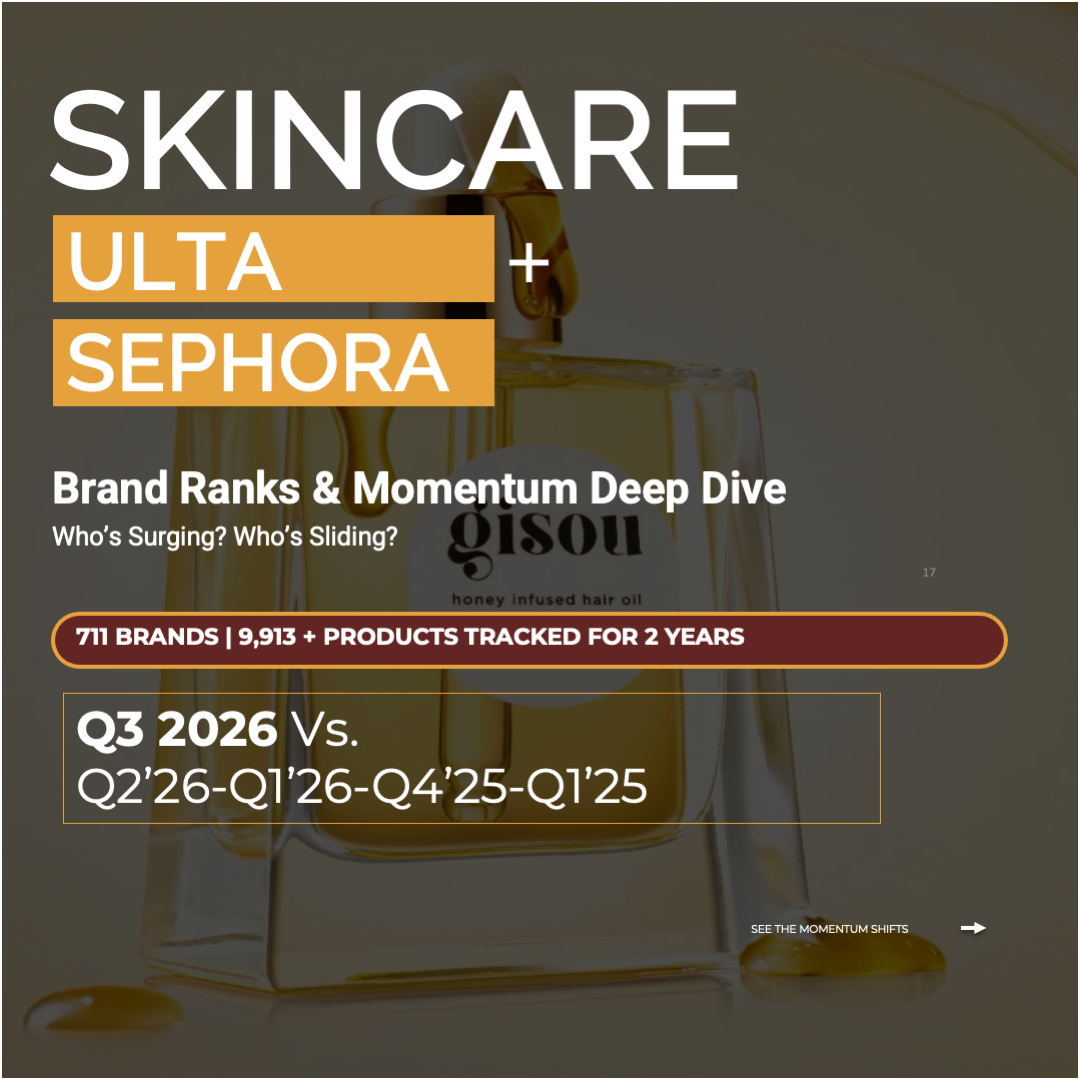
Q3 2026 Skincare: Ulta + Sephora Brand Ranks, Momentum & Competitive Intelligence Vs. Q2’26-Q1’26-Q4’25-Q1’25
$399.00
SCROLL DOWN TO PREVIEW BELOW.
Stop Guessing. Start Winning.
EXECUTIVE SUMMARY
Ulta and Sephora both sell skincare, but they run two different shelves.
The uncomfortable part: Sephora is harder to enter and harder to hold. Its ten deepest brands hold 19% of the board against 10% at Ulta, and it turns over more of its top 30 products on all 7 boards both doors run. Of 450 products ranked at both doors in both quarters, 195 moved in opposite directions. A rank at Ulta compounds. A rank at Sephora is a quarterly fight.
Ulta ranks 553 brands across 6,929 products. Sephora ranks 213 across 3,038. Only 64 brands rank on both Overall boards.
The read is downhill at both doors. In Ulta’s formula league, 215 brands are sliding against 179 climbing. La Roche-Posay, The Ordinary and Clinique lead, and the shelf is most crowded at $21 to $30, with 418 products per 10% price step against 149 at $61 to $80. At Sephora, rhode, Biodance and LANEIGE lead, 98 brands slide against 37 climbing, 32 have peaked, and the top is less stable: 13 of its Q1’25 top 30 brands are still there, against 19 at Ulta.
This report reads the shelf the way a merchant moves it: who took whose slot, at what price, and how far the board drifted underneath them.
Save thousands in consulting and hundreds of hours in research.
370+ slides · 711 brands ranked · 9,913 ranked products · 14 categories · 9 price tiers · 5 quarters
Tracked over 2 years!
Complete Data Coverage: ULTA + SEPHORA Q3’26 Vs. Q2’26-Q1’26-Q4’25-Q1’25 | Tracked over 2 years
You Get:
-
-
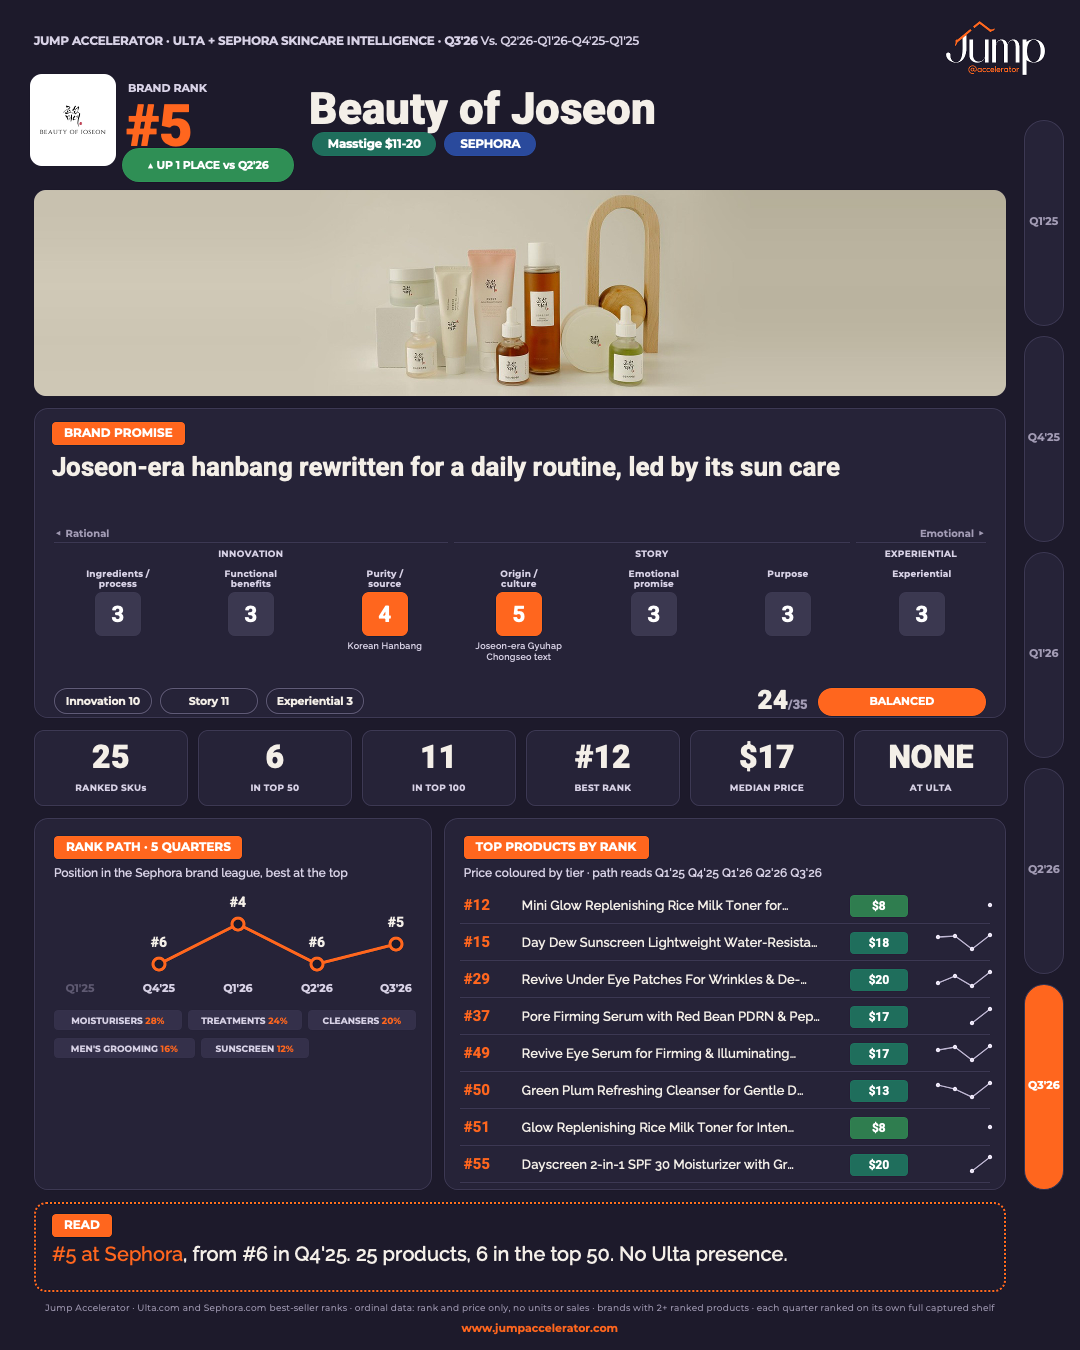
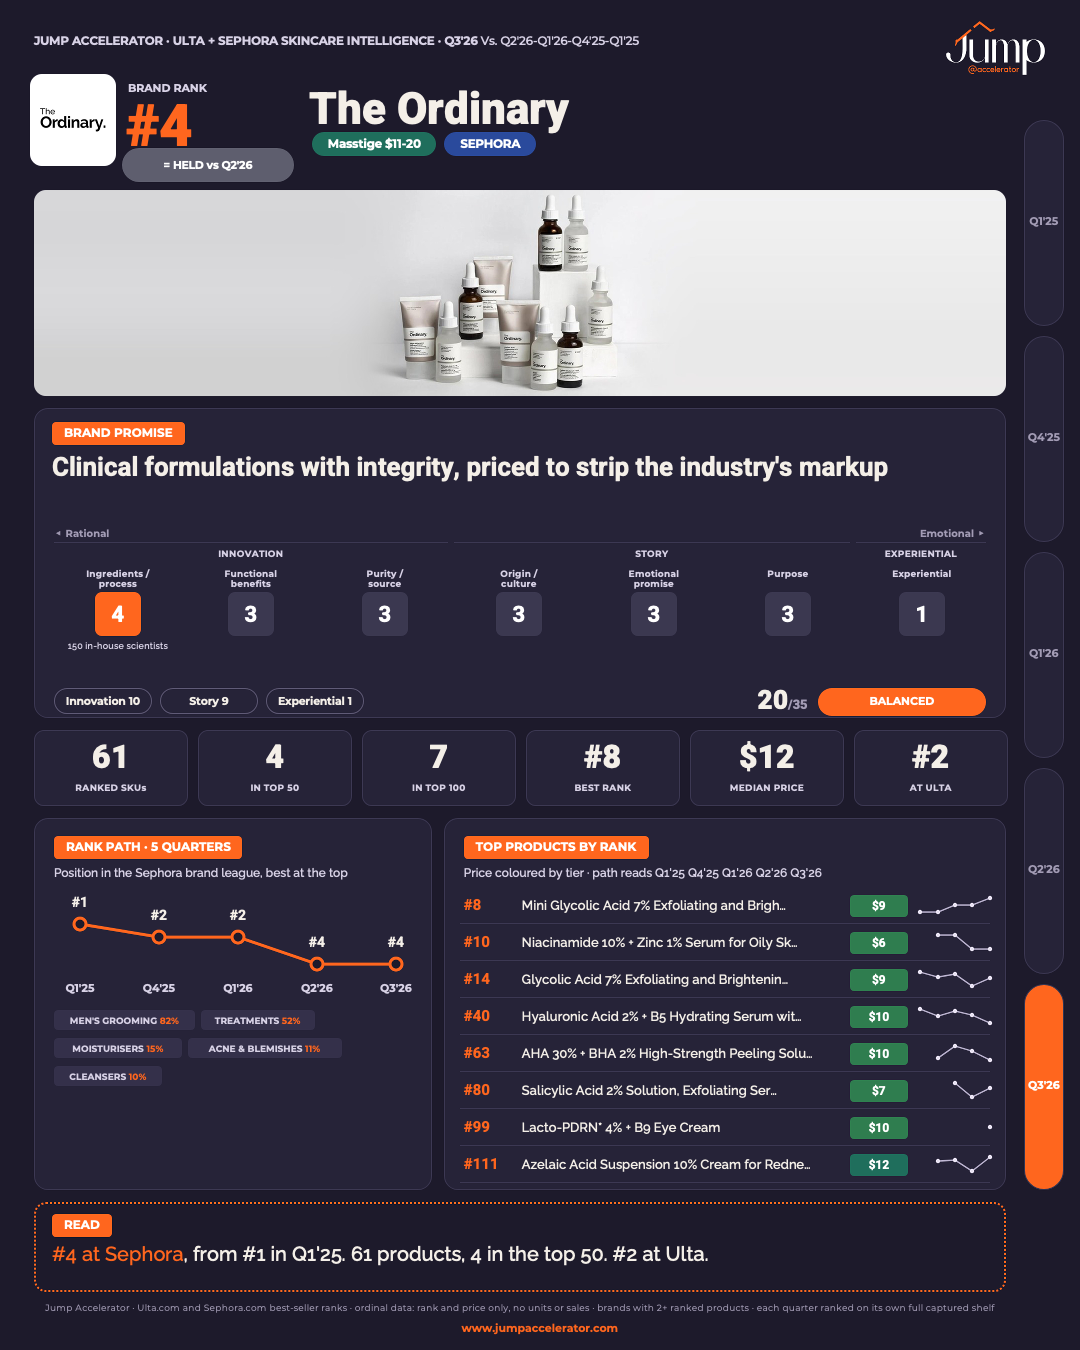
- Ten brand one-pagers: rank, trajectory, price tier, ranked footprint, top products, the other door’s rank, brand image and a seven-stopover positioning read
- Brand ranks Q3’26 against Q2’26, Q1’26, Q4’25 and Q1’25 across 22 boards at both doors: 489 brands rank only at Ulta, 149 only at Sephora, 64 at both
- Number of Top 20 and Top 50 products for each brand with its price tier, on every board
- Top 200 Brand-SKU board for every category, every product’s rank with its gain or loss on one page
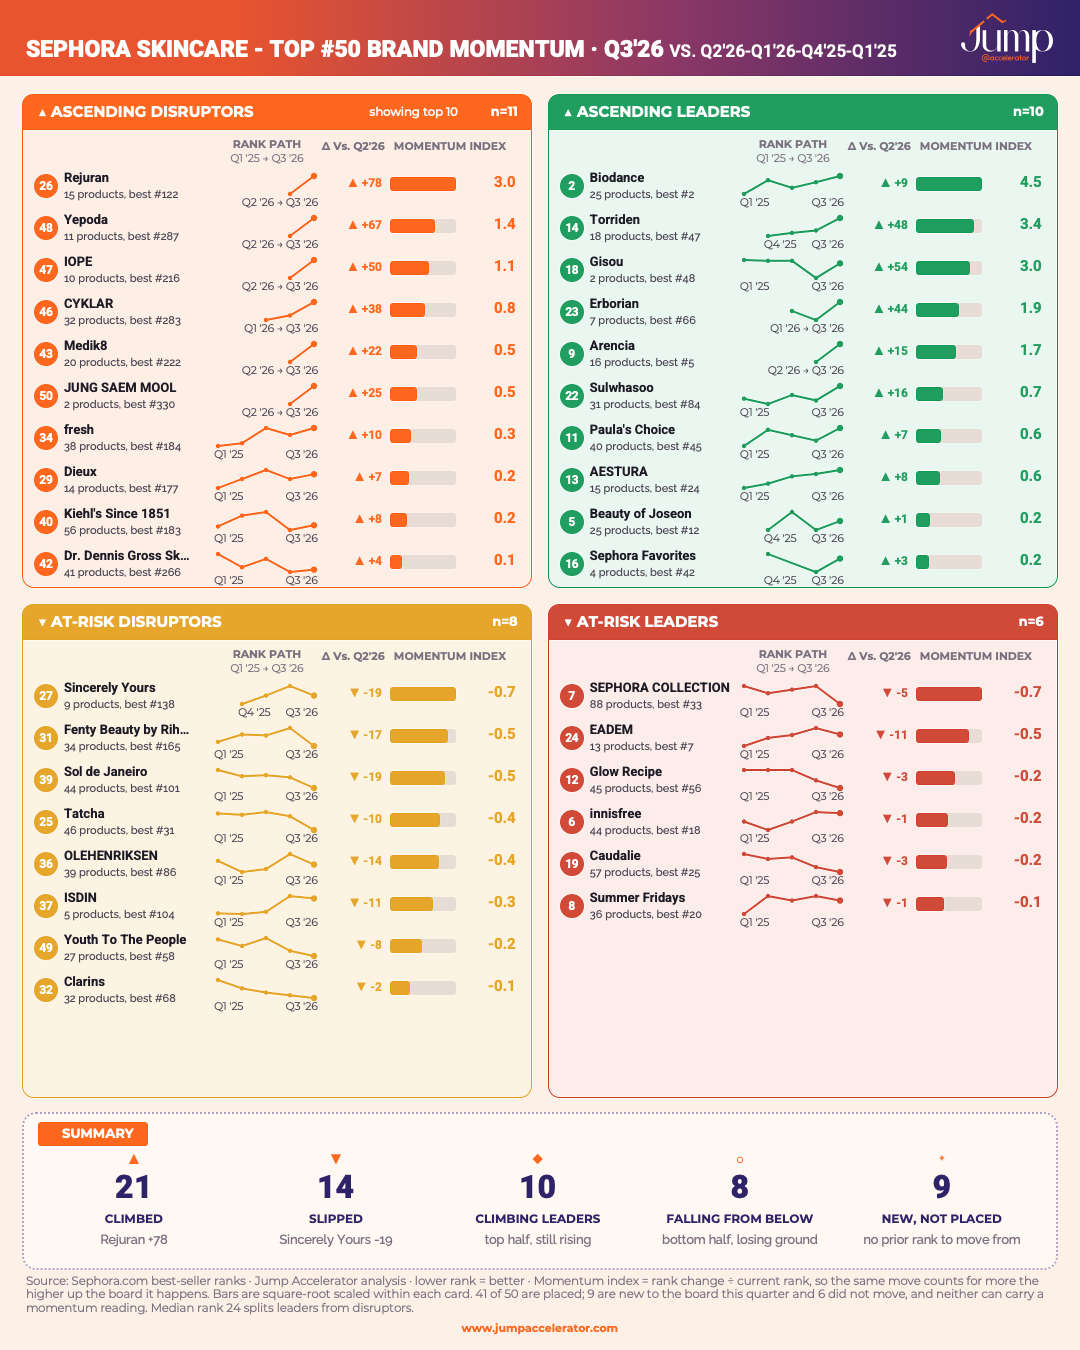
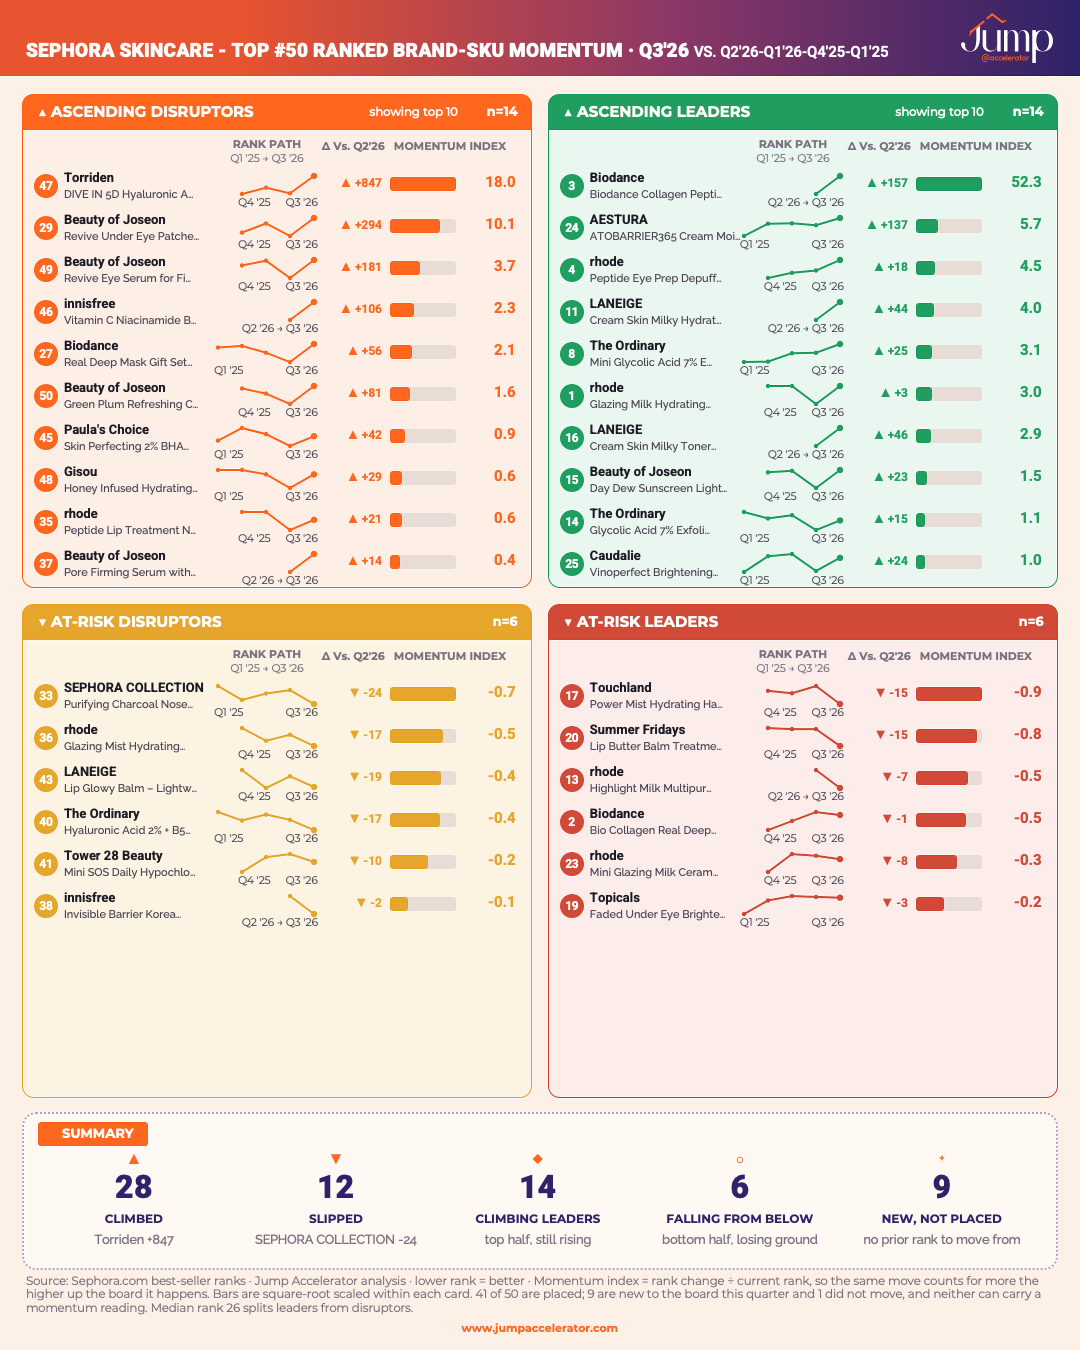
- Top 50 Brand-SKU Rank Changes & Momentum by board: Ascending Leaders, Ascending Disruptors, At-Risk Leaders, At-Risk Disruptors, on full five-quarter paths
- NEW: Three separate leagues on every overall board: brands with two or more ranked products, device and tool houses, and single-product brands, so an LED mask is never ranked against a moisturiser
- Who moved, climbers, peakers and decliners by rank band, plus exit boards separating exited, left category and off this board
- Category Saturation & Concentration: every tier re-read without its biggest brand, crowding per 10% price step, all 20 category boards side by side
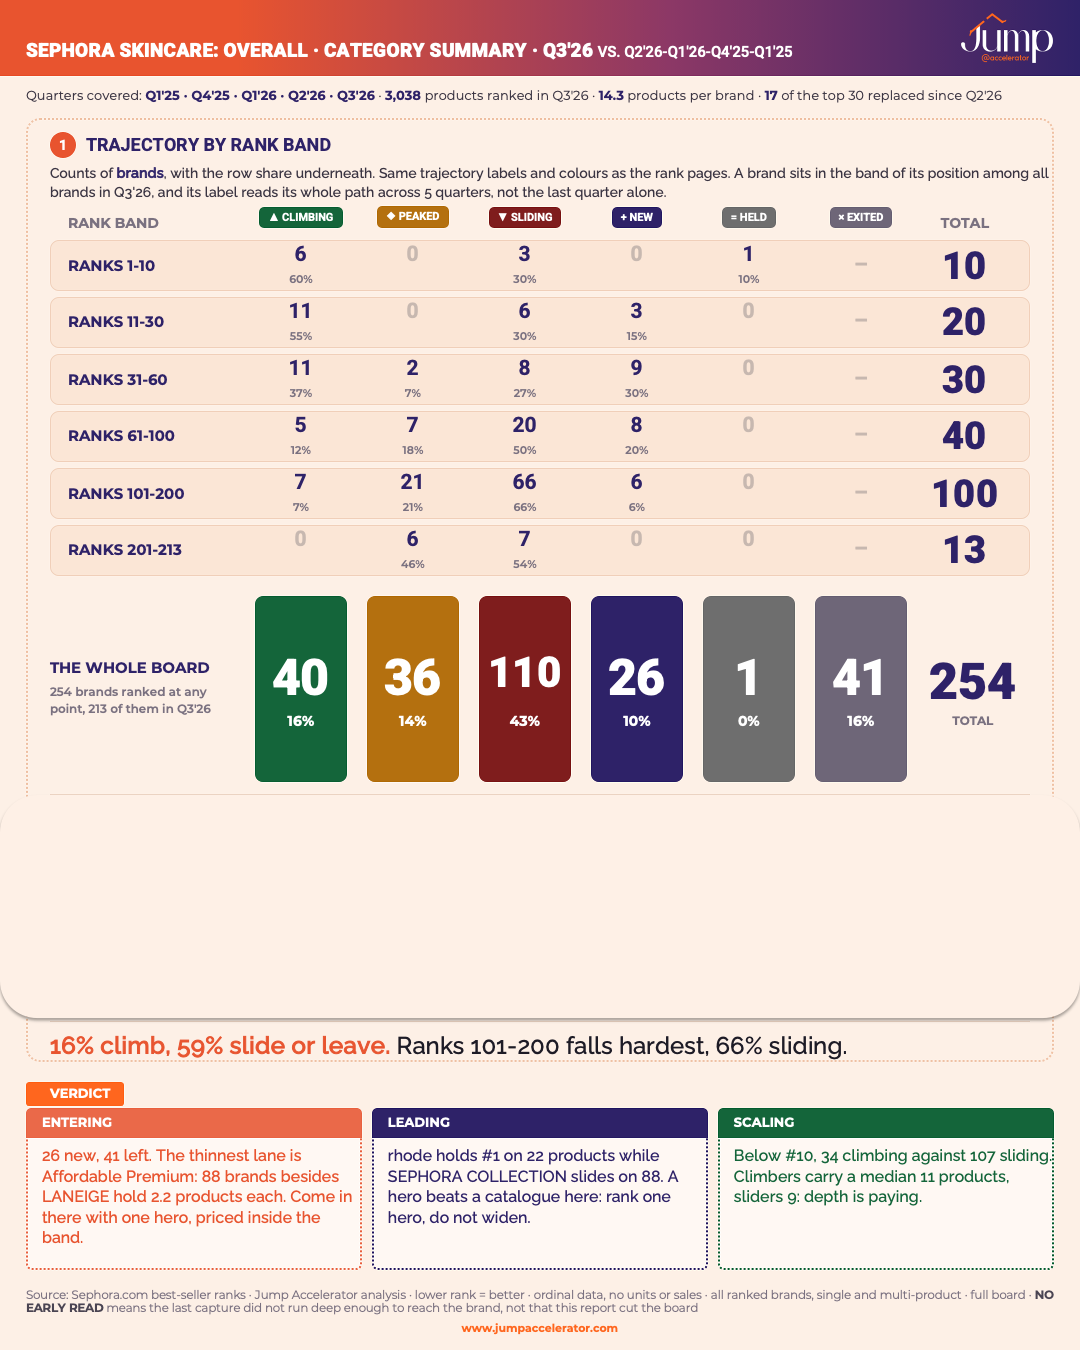
- Category Summary per board: trajectory by rank band
9 skincare categories Fully Analyzed at Ulta, 13 at Sephora:
Overall Skincare, Cleansers, Moisturisers, Serums & Treatments, Treatments, Masks, Eye Treatments, Eye Care, Lip Balms & Treatments, Suncare, Sunscreen, Anti-Aging, Acne & Blemishes, Skincare Tools, K-Beauty Skincare, Conscious Beauty, Clean Skincare, Vegan Skincare, Men’s Grooming.
Access Q3 2026 Vs. Q2 2026-Q1 2026-Q4 2025-Q1 2025 Skincare Intelligence Now!
-
750+ beauty pros trust Jump’s beauty reports.
(Save thousands(>$10K) of dollars in consulting & hundreds of hours in research & analysis)
“Refreshing, pertinent, and deeply insightful. This is the level of competitive intelligence needed to actually understand who is winning & how to win the shelf-war at Ulta and Sephora right now.” Investment Principal | Tier-1 Beauty Corporate Venture Fund
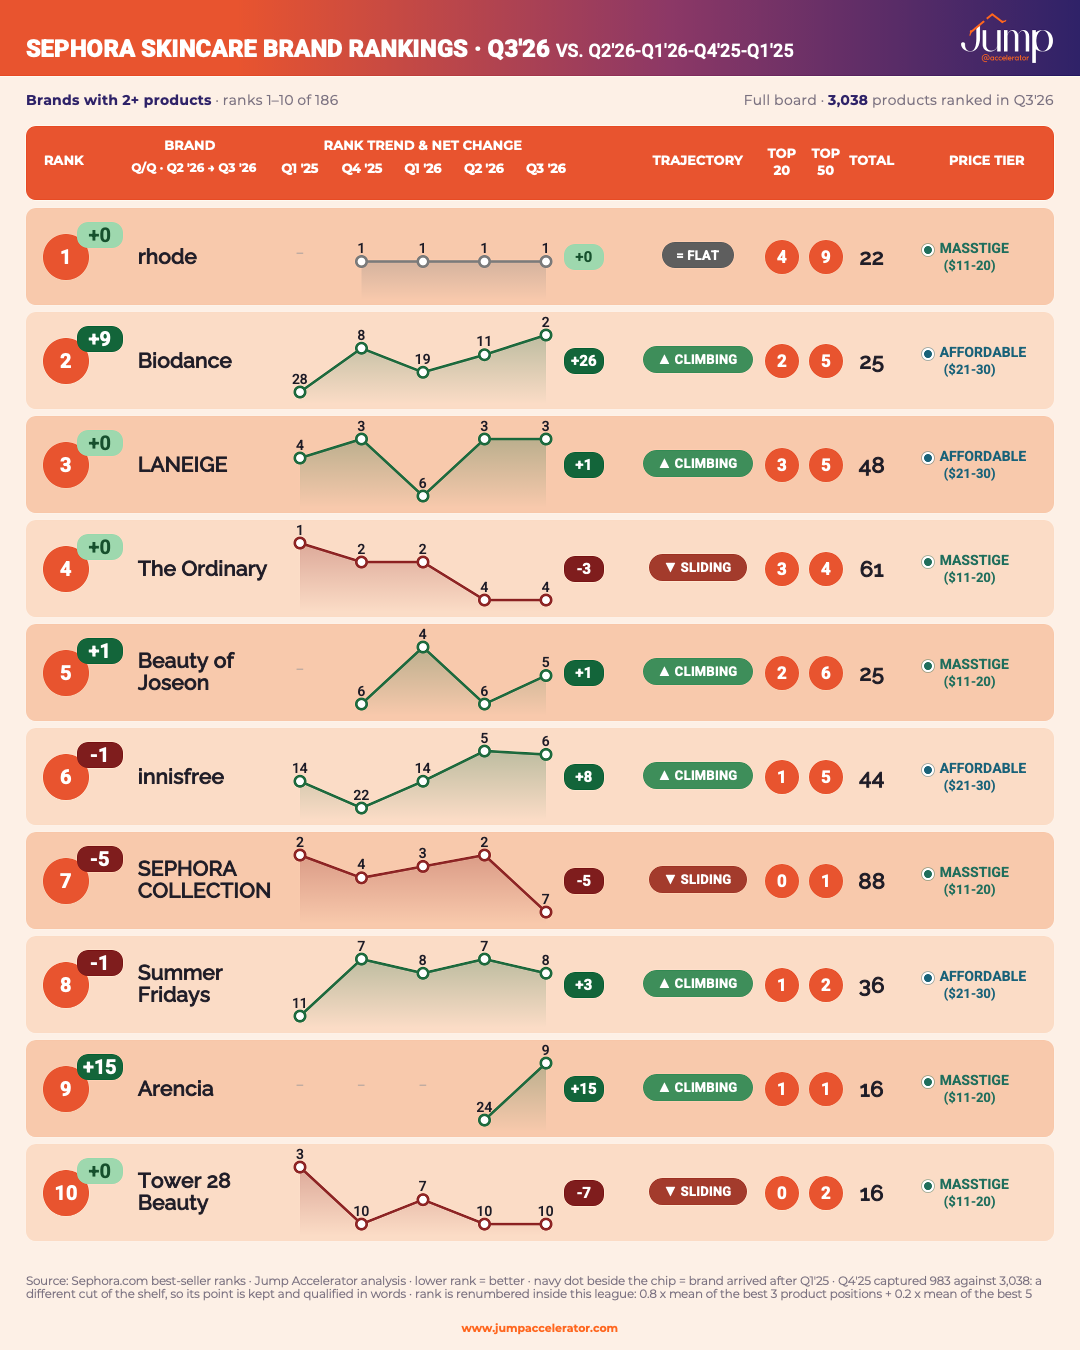
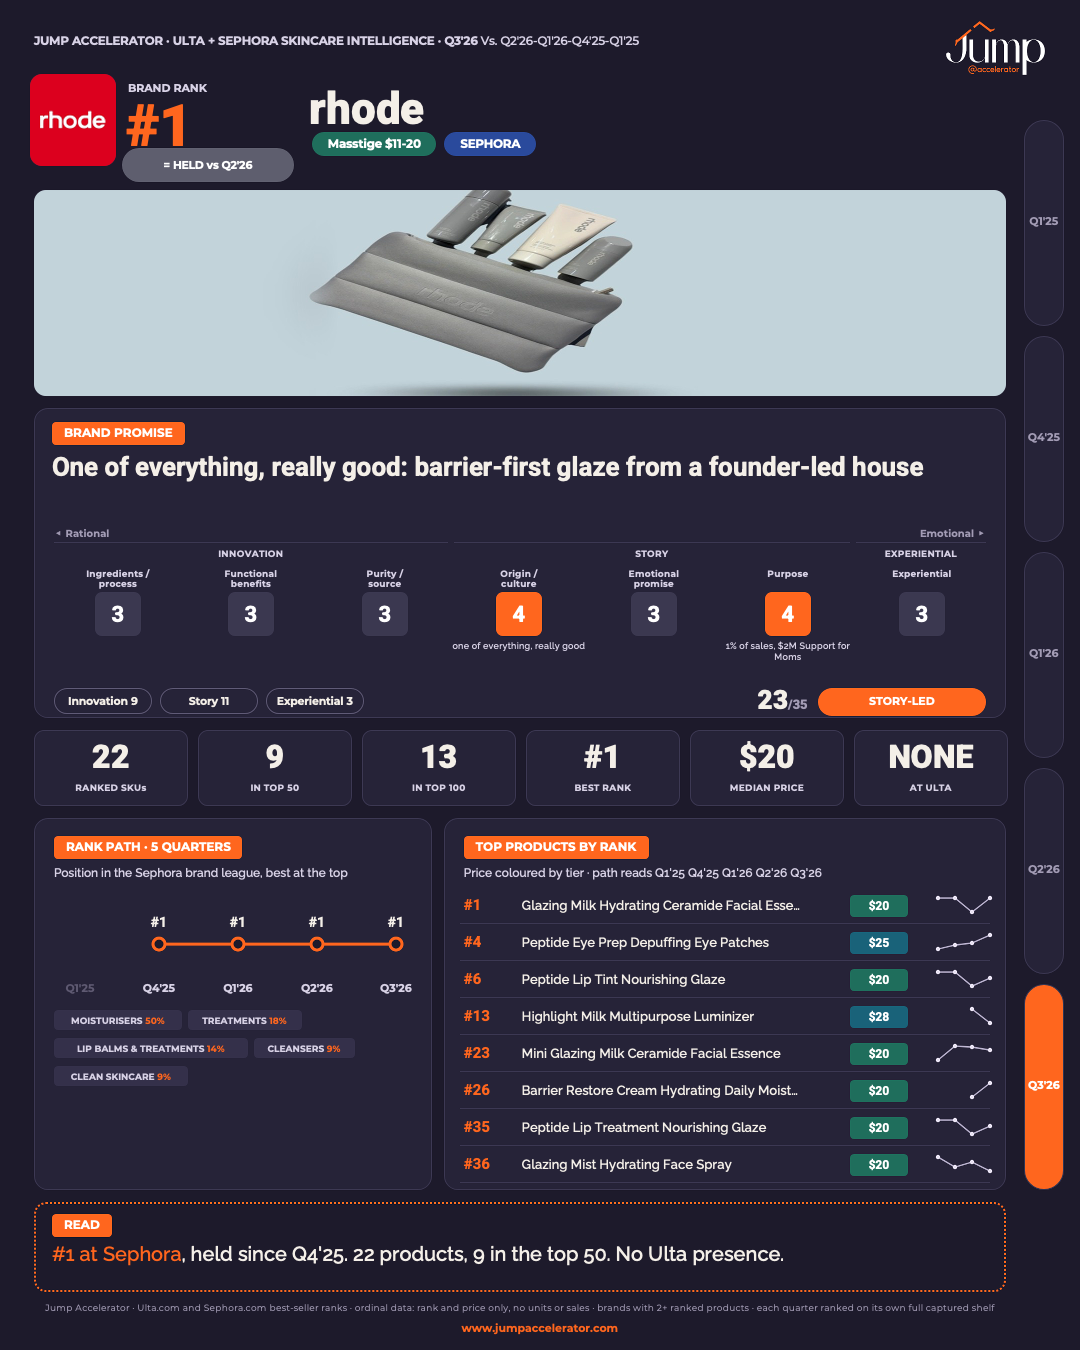
Preview
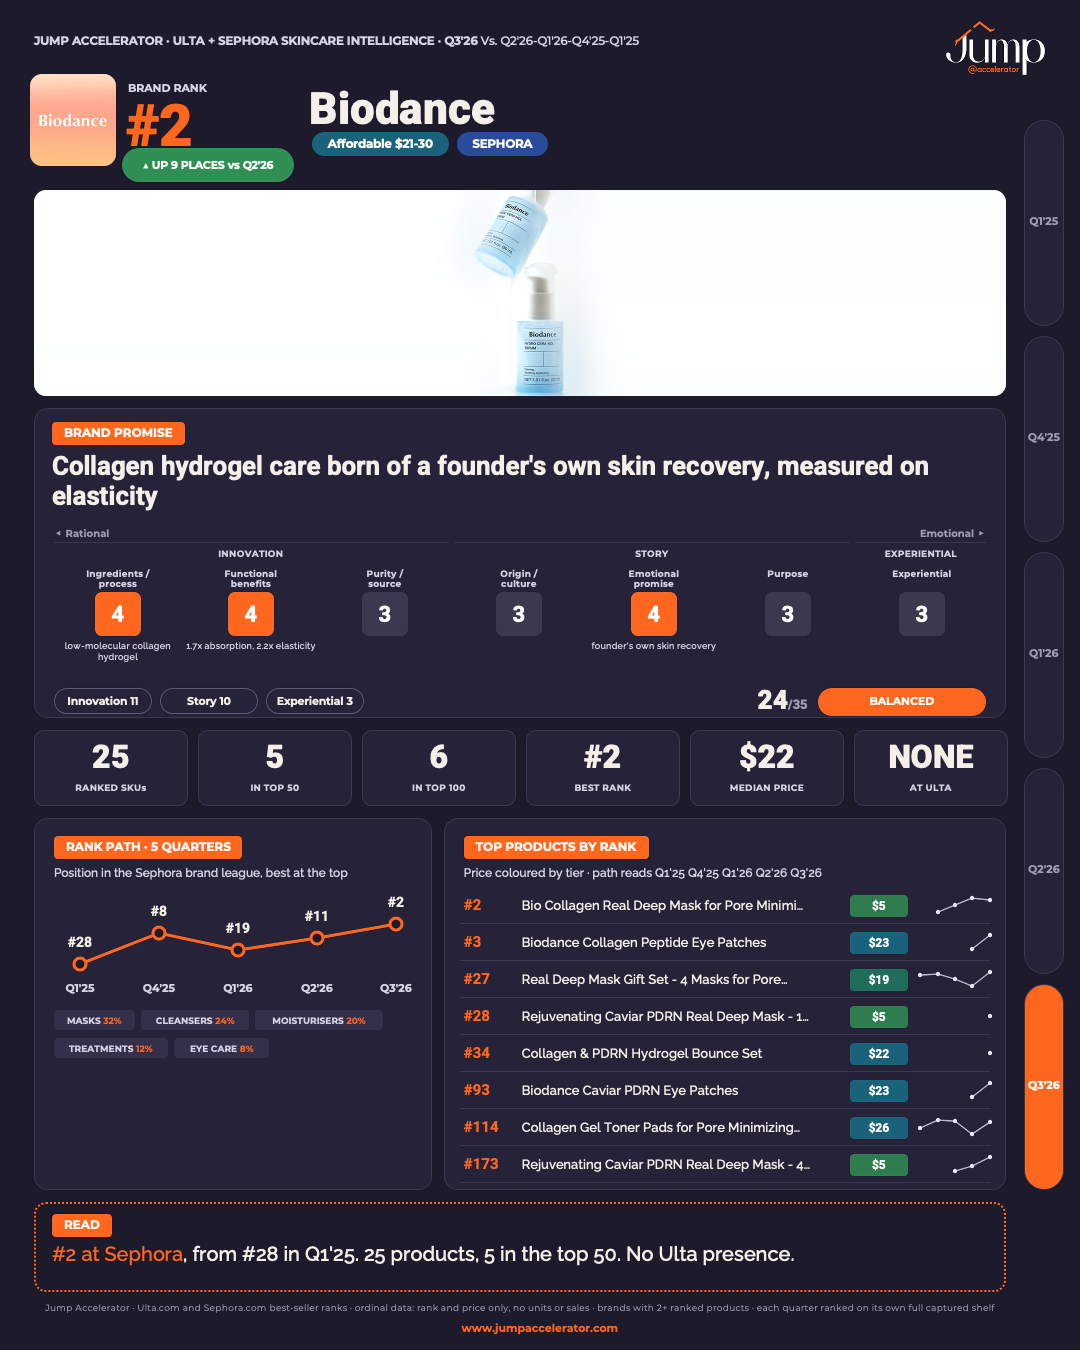
Preview
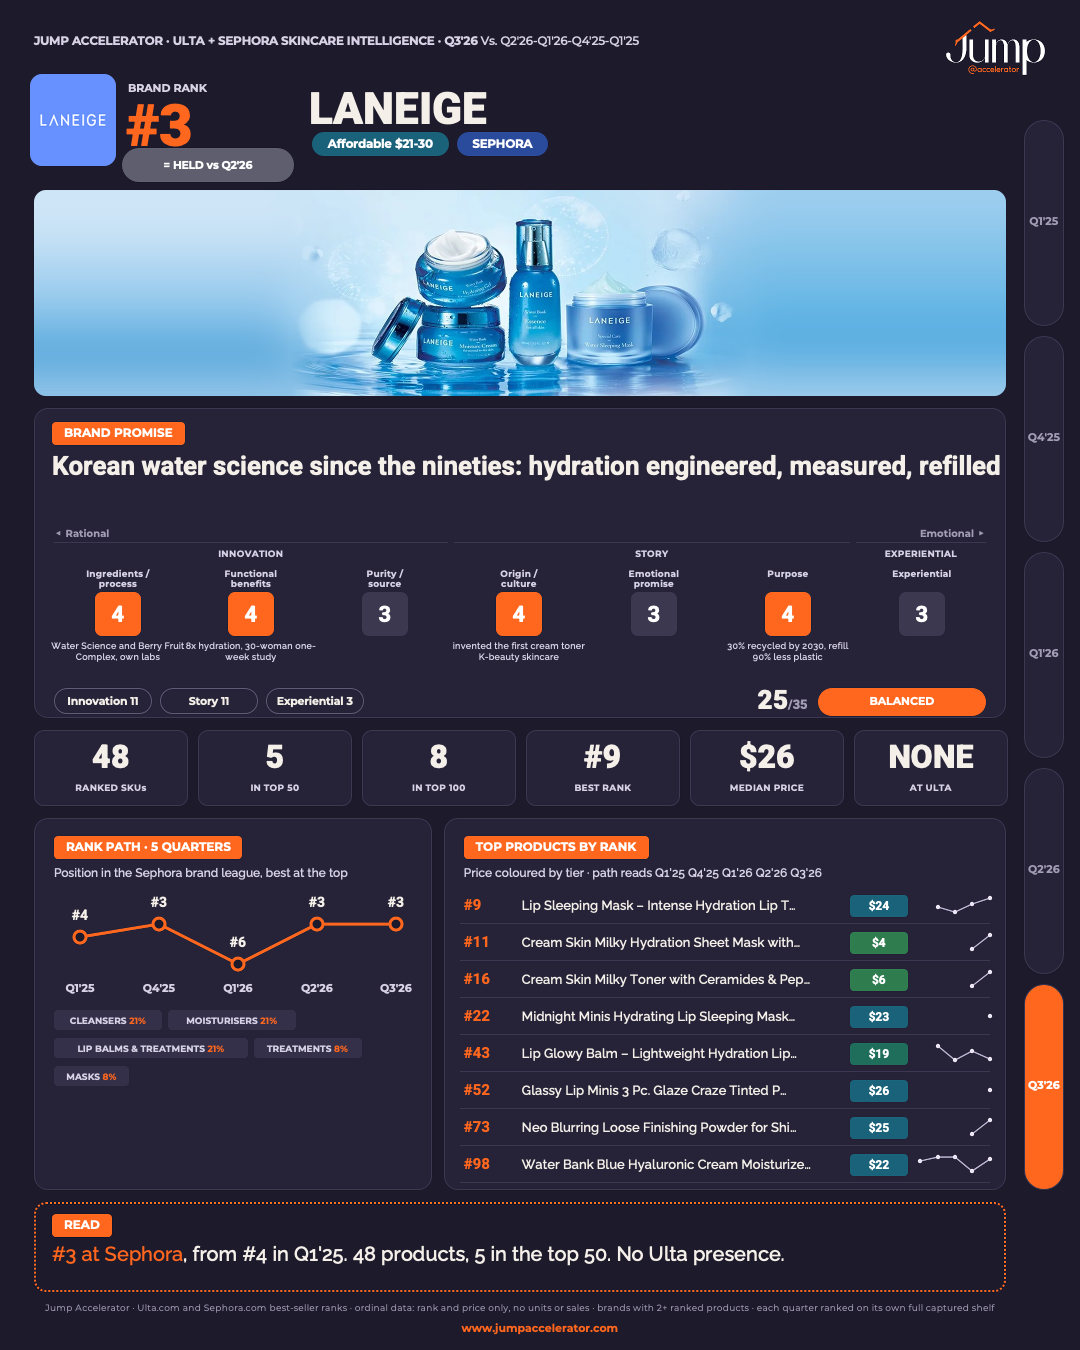
Preview
Description
DECODE THE Q3 2026 Vs. Q2’26-Q1’25 SKINCARE: ULTA + SEPHORA BRAND RANKS, MOMENTUM DEEP DIVE. THE COMPETITIVE INTELLIGENCE THAT SEPARATES A LISTING FROM SCALE.
SCALE IN 2026-27.
Who is it for?
Beauty brand founders, CMOs, investors, brand and category marketers, consultants, product developers and retail buyers
Q3 2026 Vs. Q2’26-Q1’26-Q4’25-Q1’25 Skincare Ulta + Sephora USA in
370+ slides: 711 brands, 9,913+ products, 14 categories, 9 price tiers, 5 quarters.
Tracked over 2 years!
Every block reads three ways: Entering a field, Scaling in one, Leading one.
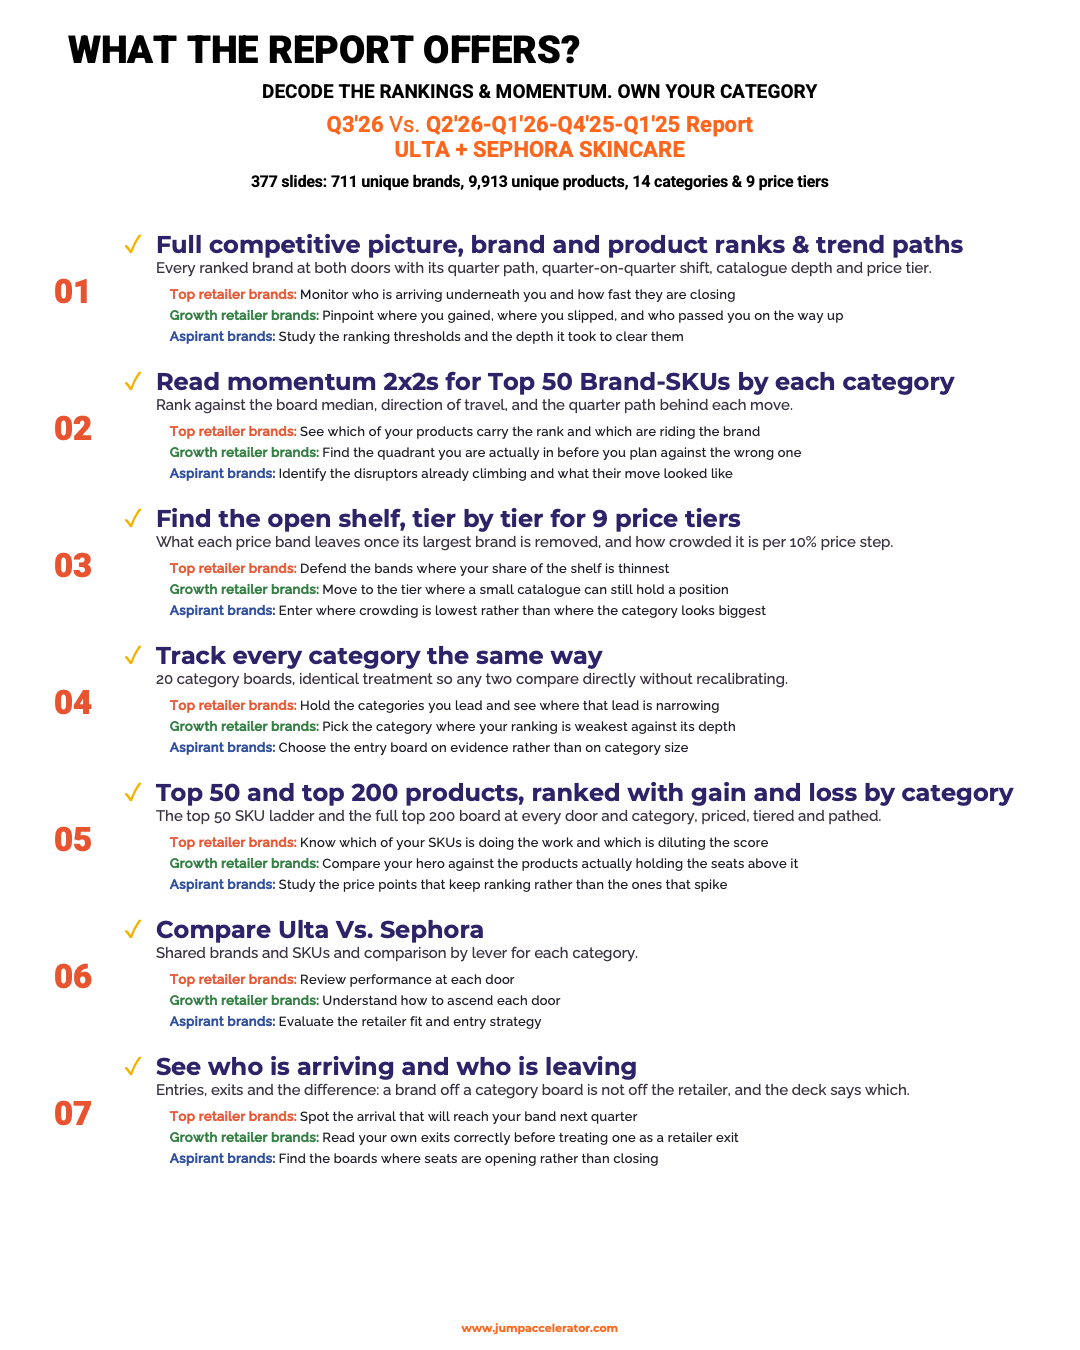
📊 See The Complete Competitive Picture + Brand and SKU Momentum
Every ranked brand at both doors: five-quarter path, quarter shift, depth, price tier, and the momentum 2x2s behind each move. 553 brands rank at Ulta, 213 at Sephora.
→ Top Retailer Brands: Spot the incumbent sliding faster than its shelf
→ Growth Retailer Brands: See which product carries your rank and which rides the house name
→ Aspirant Brands: Know the depth it takes to clear each rung
🎯 Benchmark On Rank Score, Not Catalogue Size
Formula brands, device and tool houses and single-product brands rank in separate leagues: 460, 38 and 55 at Ulta, 186, 5 and 22 at Sephora. Depth is never mistaken for strength.
→ Top Retailer Brands: See whether three products carry your rank, or thirty
→ Growth Retailer Brands: A short strong range is not punished for being short
→ Aspirant Brands: Learn the score to beat before widening the line
📈 Track Category-by-Category Performance + 20 Category Boards
Ulta’s 8: Cleansers, Moisturisers, Serums & Treatments, Eye Treatments, Suncare, Skincare Tools, K-Beauty Skincare, Conscious Beauty.
Sephora’s 12: Cleansers, Moisturisers, Treatments, Masks, Eye Care, Lip Balms & Treatments, Sunscreen, Anti-Aging, Acne & Blemishes, Clean Skincare, Vegan Skincare, Men’s Grooming.
→ Top Retailer Brands: See where your lead is narrowing
→ Growth Retailer Brands: Find where your rank is weakest against the board’s depth
→ Aspirant Brands: Pick the entry board on evidence, not category size
🚀 Master Price Architecture + What Each Tier Leaves Once Its Leader Is Removed
Nine tiers, priced at each product’s lowest size. Then every band re-read without its biggest brand: shelf per remaining brand, leader share, and crowding per 10% price step.
→ Top Retailer Brands: See which tier you are propping up
→ Growth Retailer Brands: Defend the band where your shelf is thinnest
→ Aspirant Brands: Enter where the crowd is thinnest
💡 Top 50 and Top 200 Products, Rank Changes and Momentum by Board
The top 50 SKU ladder at every door and category, priced, tiered and pathed, with the SKU momentum 2×2 behind it, plus the Top 200 board: every product’s rank and its gain or loss on a single page.
→ Top Retailer Brands: Compare your hero against the products above it
→ Growth Retailer Brands: Find the SKU doing the work and the one diluting it
→ Aspirant Brands: Study the price points that keep ranking, not the ones that spike
🏆 Climbers, Peakers and Decliners by Rank Band
Every ranked brand grouped by the direction it travelled: climbing, peaked, sliding, new, exited, read band by band, with the odds attached.
→ Top Retailer Brands: Watch the band under you fill up
→ Growth Retailer Brands: Ulta’s formula league runs 215 brands sliding against 179 climbing. Sephora’s runs 98 against 37, with 32 more past their peak
→ Aspirant Brands: Aim at the band actually turning over. Sephora’s 18 new formula brands this quarter are led by a Korean wave: Abib, WELLAGE, FULLY, Cell Fusion C, beplain, ma:nyo
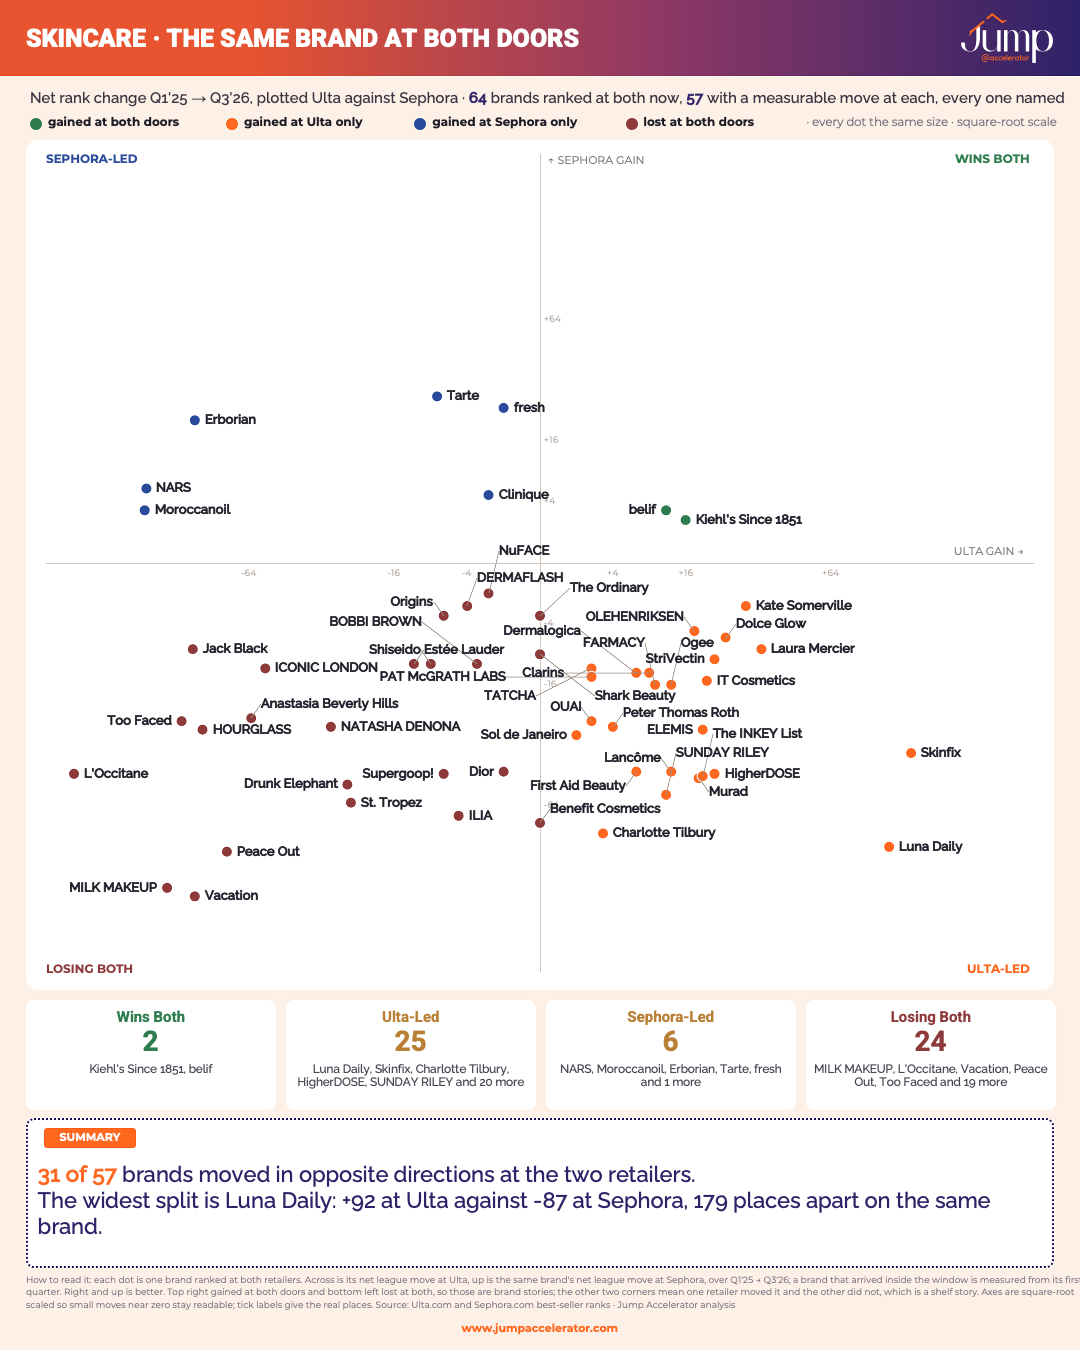
🚀 The Two-Door Read + Where Ulta and Sephora Disagree
Brand divergence and SKU movement across both addresses: who ranks at one door only, and who moves opposite ways at the same time. Of 450 products ranked at both doors in Q2’26 and Q3’26, 195 moved in opposite directions.
→ Top Retailer Brands: Catch the door slipping while the other holds. Of 64 shared brands, 24 lost ground at both
→ Growth Retailer Brands: 19 of Ulta’s Q1’25 top 30 brands are still in its top 30. At Sephora, 13. A place at Ulta holds and a place at Sephora is re-earned
→ Aspirant Brands: Choose the door your price and depth already fit
💡 Brand One-Pagers + Positioning On Seven Stopovers
Each carries rank, trajectory, tier, footprint, the other door’s rank and a 1 to 5 read on ingredients, functional benefits, purity, origin, emotional promise, purpose and experiential, with evidence behind every 4 and 5.
→ Top Retailer Brands: See where your centre of gravity has drifted
→ Growth Retailer Brands: Read the leaders’ promise against yours, stopover by stopover
→ Aspirant Brands: Take an angle no incumbent at your price owns
🧭 Verdicts: 20 Category Boards
→ Category Summary: Trajectory by rank band on every board, so the odds of climbing against sliding sit next to the ranks
How do We Collect Data?
Our Market Dominance Index methodology prevents data distortion by weighting sustained performance over viral moments. Stop making category decisions based on gut instinct BUT dominate with the complete competitive picture.
(Save tens of thousands of dollars in consulting and hundreds of hours in research and analysis.)
750+ Beauty PROs trust Jump Reports.
Access the Q3 2026 Ulta + Sephora USA Skincare Intelligence Report now!
Related products
-
 Jump Market: Omni-Channel Retail & Funds
Q3 2026 Haircare: Ulta + Sephora Brand Ranks, Momentum & Competitive Intelligence Vs. Q2’26-Q1’25
$399.00 Add to cart -
 Jump Market: Omni-Channel Retail & Funds
Q3 2026 Fragrance: Ulta + Sephora Brand Ranks, Momentum & Competitive Intelligence Vs. Q2’26-Q1’26-Q4’25-Q1’25
$399.00 Add to cart -
 Jump Market: Omni-Channel Retail & Funds
Q2 2026 Skincare: Ulta + Sephora Brand Ranks, Momentum & Competitive Intelligence Vs. Q1’26-Q1’25
$399.00 Add to cart